For your own accounts, while it is still yours to decide · focused guide
Sort your accounts out while it is still your decision.
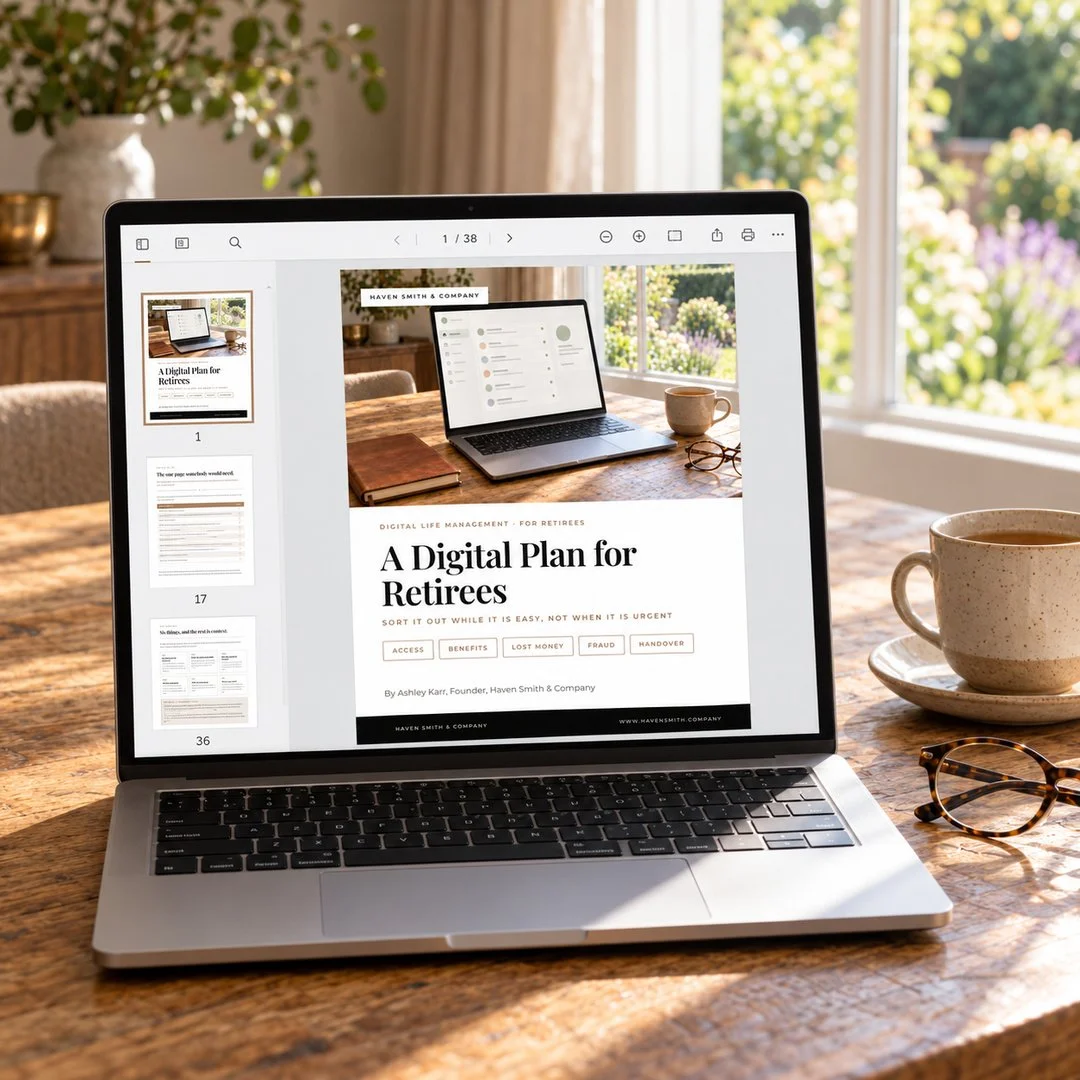
The accounts, the access, the government logins and the money you may have mislaid, put in order by you rather than by somebody else later. We publish a guide for people helping a parent. This is the one you read so that nobody has to. By the end there is one page you could hand to somebody you trust, on a day you choose.
This guide is one of the titles in The Digital Life Management Library. The Library is $299 and includes everything we publish.
- The four things that hold it up — one anchor address you own, a password manager, the codes, and the one phone they all go to
- The way in when it is not you asking — a recovery contact for now, a legacy contact for later, and the arrangement for the fortnight you cannot answer
- The government side — the Social Security login that changed, the two Medicare dates, and the surcharge form almost nobody is told about
- Money you may have mislaid — the federal database, the state searches, and tracing an old retirement account in order
- Fraud without the fear — what takes the money, six defenses in order, and the first twenty-four hours
- An ebook — PDF, instant download, no login
It downloads the moment you pay. There is no account to make and nothing to log back into, and you have seven days to change your mind.
What it is for
The version of this work you can still do yourself.
It is for the afternoon you decide the accounts are going to be in order, and you are the one deciding.
It is for the conversation where you tell somebody where things are, rather than the one where they find out afterward.
It is for the Monday a hospital asks who handles the bills and there is an answer written down.
What is in it
Seven parts, and the order is the point.
Have less before you organize what you have. Then the four things everything else rests on, then the way in when it is not you asking, then the government, the money, the fraud and the health paperwork. Each part ends with the short version, so you can do one sitting and stop.
Why the easy version is now
The same job, from the two directions. What being helped really looks like, said plainly. If you are still working there is one deadline worth knowing. And why having less comes before organizing what you have.
The four things that hold it up
One address you own and keep for good. A password manager, and the key you can hand to somebody. The codes, and the one phone they all go to.
The way in, when it is not you asking
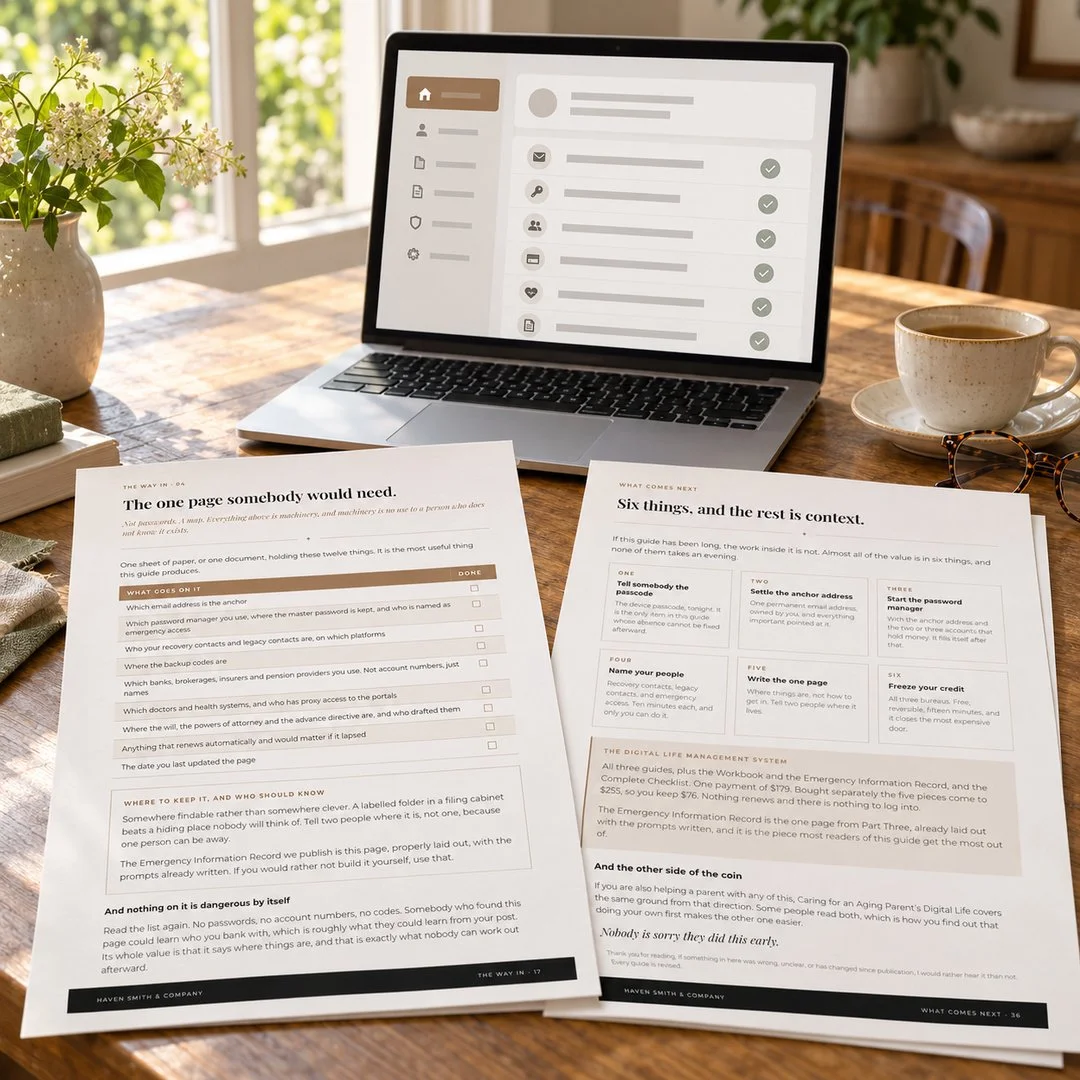
Somebody who can get you back in while you are here, somebody named for after, the arrangement for the fortnight you cannot answer, and the one page somebody would need.
The government side
Your Social Security username stopped working on 7 June 2025 and Login.gov or ID.me are now the only two ways in. Medicare open enrollment runs 15 October to 7 December, and the plan has to receive your request by 7 December. The income-related surcharge on your premium, calculated from a tax return filed while you were still working, and the form that fixes it. The federal paper check has ended, and the IRS uses a different login from Social Security.
Money you may have mislaid
The federal database that is easy to miss, three more places worth searching, one caution about a service that asks for your Social Security number, and how to trace an old retirement account in order from cheapest to most effortful.
Fraud, without the fear
What takes the money is not the phone call about a computer virus. Six defenses in the order we would do them, and what to do in the first twenty-four hours.
Health, and the paper that goes with it
Patient portals and letting somebody in before you need to. Three documents and what none of them can do. And why the settings you made in 2019 outrank your will.
The thing we will not do on this page
You do not fall for more scams. You lose more when one lands.
Every year the Federal Trade Commission publishes what people reported to it, broken down by age, including how often a report came with money lost. People in their seventies lost money in 24 percent of the frauds they reported, and people over 80 in 21 percent. People in their twenties lost money in 44 percent. The FTC told Congress the same thing: about 74 percent of older adults’ fraud reports showed no money lost at all.
The right-hand column is where the real problem is. The median loss for people in their seventies was $1,000, and for people over 80 it was $1,650. For people in their twenties it was $417. Fewer frauds land, and the ones that do cost four times as much.
That is the guide’s whole posture. We are not going to frighten you about your judgment. We are going to make the one that lands cost less.
Honestly
Who this is for, and who it is not.
This is for you if
- You are retired, or close enough to be thinking about it.
- You would rather set this up yourself than have an adult child do it for you later.
- You have accounts going back thirty years and no list of them.
- Somebody has offered to help and you are not sure how much to hand over.
- You want one page a trusted person could pick up and act on.
This is not for you if
- You are doing this for a parent rather than for yourself. Caring for an Aging Parent’s Digital Life is $29 and written from that side.
- What you want is the full three-month method. The Digital Life Management System is $179.
- You are looking for investment or benefits advice. This is about access and organization, and we are not licensed to advise you on either.
If you want more than this
The other side of the coin, and the full method.
This guide and the aging-parent guide are deliberately a pair. One is the work you do for yourself. The other is the work somebody does with you.
Caring for an Aging Parent’s Digital Life $29
The same job from the other direction, written for the person helping. Consent first, then access.
The Digital Life Management System $179
Three months, two hours a week, with the Workbook and the Emergency Information Record.
The Emergency Information Record $29
The one page somebody would need, properly laid out, printable and filled in by hand.
Before you buy
The questions people ask.
Do I need to be good with computers?
No. Everything is in plain language, and where a term matters we say what it means and whether it affects you. Nothing asks you to install anything you do not already have.
Is this going to tell me I am a target because of my age?
No. The guide opens with the Federal Trade Commission’s own data, which says older adults report money lost less often than younger adults do. What is true is that the losses are larger when one lands, and that is what the book works on.
I have already been helped with some of this. Is it too late?
No. The guide is built so you can start anywhere and stop after one sitting. There is a short version at the end of every part.
Does it cover Social Security and Medicare?
It covers the access and the deadlines: the login that changed in June 2025, the open enrollment window, and the form that corrects an income-related premium surcharge. It does not advise you on which plan to choose.
Is this legal or financial advice?
No. It is education about organizing information and about who can reach what. Where something matters, take it to a professional who is licensed to advise you.
Do I need an account to open it?
No. It downloads the moment you pay and it is yours on your own computer.
Can I get a refund?
Yes. Write to us within seven days and we will refund you.
The easy version of this work is the one you do now.
Access, the government side, the money, and the one page somebody would need. Written down, and still yours to change. One payment of $29.
Instant download · No login · Seven-day guarantee